Auction finance, ready before the hammer falls
Bridging finance for property investors buying at auction, with a straightforward view of what's fundable, usually the same day.
28 days goes quickly
At a traditional auction, the hammer is exchange of contracts. You usually have 28 days to complete, and if you miss the deadline, you can lose your deposit and face a claim for the seller's losses.
A standard mortgage rarely completes in 28 days, and many auction lots can't be mortgaged as they stand. That's why most financed auction purchases use bridging finance, and why it needs to be lined up before you bid.
Buying a property that needs work? Read about refurbishment bridging.
How DGL helps auction buyers
Before you bid
An agreement in principle for your maximum bid, so you know where you stand.
The legal pack
We check the pack and lot details with lenders early, so problems surface before the hammer, not after.
The right lender
Matched to your property and your timescale, able to complete inside the auction deadline.
The exit
We line up your refinance or sale alongside the bridge, so you're never left with expensive short-term debt.
Funding in place, fast
We arranged a £750k bridge (65% of the purchase price) to secure a £1.15m light industrial park in West Yorkshire, then lined up term refinance terms once the client had re-let the units.
How it works
- 1
Tell us about the lot: the address, the guide price and your plans for the property.
- 2
We give you a straightforward view of what's fundable and an agreement in principle.
- 3
You bid with confidence, knowing your maximum.
- 4
After the hammer, we submit the full application and instruct the valuation.
- 5
The lender completes inside your deadline, and we line up the exit.
Frequently asked questions
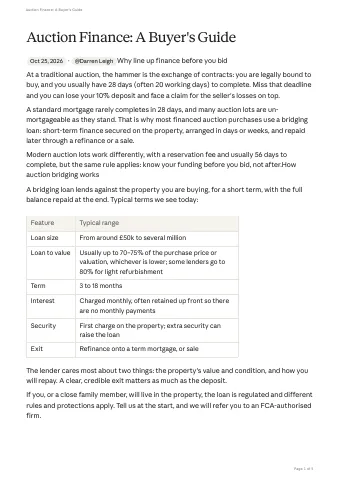
Free guide: Auction Finance, A Buyer's Guide
Everything you need before auction day: the 28-day deadline, what bridging costs, the legal pack red flags that stop lenders, and a pre-auction checklist.
DGL Commercial Finance Ltd is not authorised or regulated by the Financial Conduct Authority. We arrange unregulated finance for property investors, developers and businesses only. Where a loan would be regulated, we will refer you to an FCA-authorised firm. All finance is subject to status, valuation and lender approval. Your property may be repossessed if you do not keep up repayments on a loan secured on it.